Contents
The Absolute Must-Know Details of the January 31, 2026 Deadline
- Sole Traders: Individuals who are self-employed with an income over £1,000 before tax allowances.
- Landlords: Individuals receiving income from renting out property (unless it is covered by the property allowance).
- Partnerships: Partners in a business partnership.
- High Earners: Individuals whose income was over £100,000.
- Individuals with Complex Income: Those with foreign income, certain investment income, or income from trusts.
- Simple Assessment Customers: Individuals who received a letter from HMRC stating they owe tax, even if they have not traditionally filed a full Self Assessment.
- Balancing Payment: The final amount of tax owed for the 2024/2025 tax year.
- First Payment on Account (POA): The first of two advance payments towards your estimated 2025/2026 tax bill. The second POA is due on July 31, 2026.
The Hidden Urgency: How the 2026 Deadline Triggers Making Tax Digital (MTD)
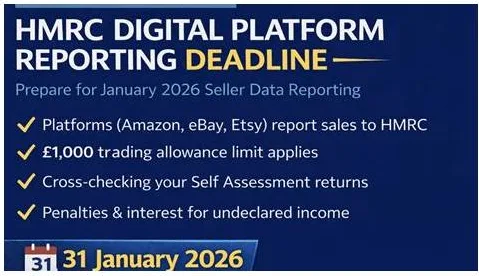
The most significant, and often overlooked, aspect of the January 31, 2026 deadline is its direct link to the commencement of Making Tax Digital for Income Tax Self Assessment (MTD-ITSA). This is the government's mandatory initiative to digitise the tax system for millions of sole traders and landlords. MTD-ITSA: The £50,000 Threshold The MTD-ITSA regime is being rolled out in phases. The first phase, which begins on April 6, 2026, mandates compliance for sole traders and landlords whose total annual gross income from self-employment and/or property exceeds £50,000. The Self Assessment tax return you file by January 31, 2026, for the 2024/2025 tax year, is the mechanism HMRC will use to assess your income and determine if you cross this £50,000 threshold.- If your 2024/25 income is over £50,000: You will be mandated to comply with MTD-ITSA from April 6, 2026. This means you must start using MTD-compatible software to keep digital records and submit quarterly updates to HMRC.
- If your 2024/25 income is below £50,000: You will not be mandated in the first phase, but you should prepare for the second phase, which will apply to those with income over £30,000 from April 6, 2027.
- Digital Record Keeping: Using specific software to record all business transactions.
- Quarterly Updates: Submitting a summary of income and expenses every three months.
- End of Period Statement (EOPS): A final annual declaration replacing the traditional Self Assessment.
Navigating Penalties and Payment: Your Guide to HMRC Compliance
The penalties for missing the January 31, 2026 deadline are severe and accrue quickly, designed to encourage timely filing and payment. The Escalating Penalty Structure HMRC’s penalty system for late filing is structured as follows:- Day 1 (February 1, 2026): An immediate £100 fixed penalty, even if you owe no tax or pay your tax on time.
- After 3 Months (May 1, 2026): Daily penalties of £10 are applied, up to a maximum of £900.
- After 6 Months (August 1, 2026): A further penalty of 5% of the tax due or £300, whichever is greater.
- After 12 Months (February 1, 2027): Another penalty of 5% of the tax due or £300, whichever is greater. In serious cases, this can increase to 100% of the tax due.
- File your 2024/25 Self Assessment tax return on time (by January 31, 2026).
- Owe £30,000 or less.
- Not have any other outstanding tax returns or debts.
- Set up the arrangement no later than 60 days after the payment deadline.
- HMRC: Her Majesty's Revenue and Customs, the UK's tax authority.
- Self Assessment (SA): The system used to collect Income Tax.
- Making Tax Digital (MTD): The government's program to digitise the tax system.
- MTD-ITSA: Making Tax Digital for Income Tax Self Assessment.
- Payment on Account (POA): Advance payments toward the next year's tax bill.
- Tax Year 2024/2025: The period for which the tax return is due (April 6, 2024 to April 5, 2025).
- Tax Agent/Accountant: The professional who can file on your behalf.